Publications /
Policy Brief
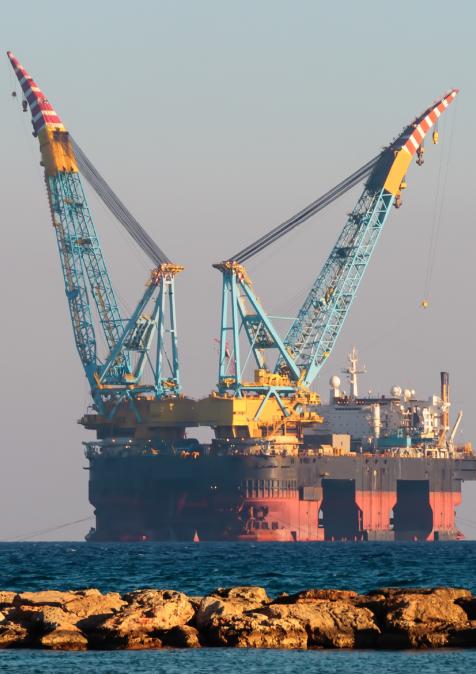
Since around 2010, it has been known that the Eastern Mediterranean is a new gas province. Gas resources have indeed been discovered offshore four countries or territories: Egypt, Israel, Cyprus and Gaza. Two of them have become producers and exporters of natural gas, Egypt and Israel. Off the coast of Gaza, the Gaza Marine gas field has never been developed, and it is highly unlikely to be developed anytime soon given the very high tensions between the State of Israel and Hamas. By contrast, several gas discoveries have been made off the Republic of Cyprus, which will become the region’s third gas-exporting country.
Cyprus will become a gas exporter 17 years after the first offshore discovery
For Cyprus, the countdown has begun. The country, a member of the European Union (EU), is expected to become a producer and exporter of natural gas as early as 2028. According to the Cypriot Ministry of Energy, Commerce and Industry, production could begin as early as the first half of 2028. This will be the culmination of a long journey, since the first offshore gas discovery, Aphrodite, was made in 2011 by the American company Noble Energy (in this Policy Brief, we discuss only gas discoveries beneath the Eastern Mediterranean, not those made onshore in countries of the region). Noble Energy, which pioneered exploration in this area, was acquired by Chevron in 2020.
There will therefore be a gap of at least 17 years between the first offshore discovery in Cyprus and the first gas field entering production. But that field will not be Aphrodite, located on block 12 of Cyprus's Exclusive Economic Zone (EEZ), but Cronos on block 6, held in equal shares by the Italian energy group Eni and TotalEnergies. Eni operates this exploration licence, on which Cronos was discovered in 2022. On July 28, 2026, the two companies took the final investment decision for the development of Cronos. It will be the first gas field to enter production in Cyprus's history, just six years after its discovery. Its gas initially in place (GIIP) is estimated at more than 85 billion cubic metres. Given this volume, Eni and TotalEnergies are planning a production plateau of 500 million cubic feet per day (MMcf/d), or around 5.2 billion cubic metres per year.
Monetizing the gas as the main challenge
When gas is found beneath the Eastern Mediterranean, even in deep water as is the case for Cronos, the main difficulty is not extracting it but monetizing it. One of the strengths of the Eni/TotalEnergies project is that the two partners will make maximum use of existing infrastructure, which offers a triple advantage: shorter lead times before production start-up (only around two years after the investment decision, which is very fast); lower costs; and reduced greenhouse gas emissions. To achieve this, gas from Cronos will be carried through a new pipeline to the offshore Zohr field in Egypt, operated by Eni. From there, it will travel through the existing pipeline linking Zohr to an onshore gas processing plant in Egypt. A new pipeline will then need to be built from that plant to the Damietta LNG plant on Egypt's Mediterranean coast, where the gas will be converted into liquefied natural gas (LNG). The LNG will finally be loaded onto LNG carriers for export to international markets, mainly in Europe. Gas production of 500 MMcf/d will translate into 2.8 million tonnes (Mt) of LNG per year. Eni and TotalEnergies will each sell 1.4 Mt/year. The terms for using the existing infrastructure and facilities have already been defined, which will save valuable time in carrying out the project.
Economic and geopolitical impacts
The impacts of this future production start-up are both economic and geopolitical, and concern the companies leading the project, Cyprus, other countries in the region, the EU, and the gas market. The development of Cronos and its future entry into production will strengthen the positions of Eni and TotalEnergies in the Eastern Mediterranean, a gas province where the two European firms are already key players. They are not the only ones, however, since Chevron, ExxonMobil, and QatarEnergy are also active in the area. Eni and TotalEnergies hold stakes in three other offshore exploration licences in Cyprus, blocks 7, 8 and 11, and they are gaining an edge over their competitors by being the first to bring a gas field into production in the country.
Another positive factor for Eni and TotalEnergies is that developing Cronos will make it easier to monetize other gas resources on block 6. Cronos is indeed not the only discovery on this licence: there have been two others to date, Calypso and Zeus. TotalEnergies has stated that these two discoveries will be subject to appraisal work, aimed at determining whether the fields are commercially viable. Lastly, the Cronos project will help strengthen the LNG portfolios of both groups. TotalEnergies, which describes itself as the world's third-largest player in the LNG industry, aims to reach an LNG portfolio of 60 Mt/year. In 2025, its global LNG sales stood at 44 Mt/year. Eni aims to expand its contracted LNG portfolio to more than 20 million tonnes per year by 2030.
Very good news for Cyprus and for the European Union
Beyond these implications for Eni and TotalEnergies, the launch of Cronos's development is very good news for the Cypriot state, which is finally seeing its gas future take shape. As noted above, the first offshore discovery in Cyprus, Aphrodite, dates back to 2011, and in recent years the government of the Republic of Cyprus had shown growing frustration at the slow pace of the Chevron-led consortium (block 12). Development of a gas field has finally begun, even if on a different block, and — a second piece of very good news — production is expected to begin after a very short development period, in 2028. A major gas project means, for a country, additional tax revenue and export earnings, as well as greater strategic weight.
Cyprus will also be able to implement its plan to introduce natural gas into its electricity system, helping to diversify its sources of power generation and reduce greenhouse gas emissions. Although natural gas is a fossil fuel, its climate impact is lower than that of oil and coal. Fossil fuels still account for around 85% of electricity generation in Cyprus, comprising 84% petroleum products and 1.5% solid fuels (coal). Renewable energy accounts for 14.5%. According to the Ministry of Energy, emissions from the electricity sector could fall by 25–30% once natural gas is introduced. To this end, the country is also relying on LNG imports through two projects: an LNG import terminal to be located at Vasilikos and the acquisition of a floating storage and regasification unit (FSRU), ETYPHA Prometheus. Alongside this priority, other key elements of Cyprus's energy policy include the development of renewable energy and battery storage, the establishment of a physical interconnection with the European electricity grid and the Middle East (see inset), and the modernization of the energy market.
In addition, the agreements reached around the Cronos project mark the beginning of a regional gas hub, since Cypriot gas will be exported via Egypt using that country's infrastructure and facilities. Cyprus is a member of the East Mediterranean Gas Forum (EMGF) and maintains good relations with Egypt and Israel. For several years, Eni has argued that creating such a hub would encourage gas developments in the region, and the Italian group's patience is finally being rewarded.
More good news lies ahead. Eni and TotalEnergies could develop Calypso and Zeus, which would increase their gas production. Although development of Aphrodite on block 12 has not yet been launched, it is expected to begin in the near future, most likely in 2027, with production projected to start in 2031. Block 12 is held by a consortium made up of Chevron (operator, 35%), BG Cyprus (Shell group, 35%) and NewMed (Israel, 30%). At the end of July 2026, Shell agreed to sell its stake in block 12 to MOL Group (Hungary). This transaction is subject to approval by the Cypriot government and should be finalized in early 2027. [3] Here too, gas from Aphrodite would be transported to Egypt and sold to the national company Egyptian Natural Gas Holding Company (EGAS). On block 10, ExxonMobil (operator, 60%) and QatarEnergy (40%) have also made discoveries and recently (end of June 2026) announced that these discoveries, named Glaucus and Pegasus, were commercially viable. According to ExxonMobil, the final investment decision could be taken in 2029, with gas production potentially starting in 2033. Egypt could once again play an important role in monetizing block 10's resources.
Cypriot Minister of Energy, Commerce and Industry Michael Damianos described Glaucus and Pegasus as two of the “most significant” successes of Cyprus's offshore exploration programme. He added that the ExxonMobil-led consortium had expressed interest in other opportunities within the island's exclusive economic zone, particularly blocks 4 and 10A. According to the minister, the six gas discoveries confirmed to date across three licences could contain around 20 trillion cubic feet of natural gas (566 billion cubic metres), underscoring their substantial potential. Further discoveries also remain possible as exploration continues.
Cyprus, the European Union and Türkiye
For the global LNG market, Cronos marks the emergence of a new supplier, which can only please LNG importers. This is especially true for the EU, since Cyprus is one of its 27 member states and held the presidency of the Council of the EU during the first half of 2026 before handing it over to Ireland. The two partners in the project, Eni and TotalEnergies, are specifically targeting the European market for their future LNG deliveries. EU climate policy nevertheless presents a tension: the European Climate Law sets a binding objective of climate neutrality across the Union by 2050, in line with the goals of the Paris Agreement, requiring substantial reductions in fossil fuel consumption, including natural gas. That said, the fact that Cyprus will be in a position to enter the LNG market as early as 2028 leaves a fairly long window to sell gas to other EU countries, especially since the Union also faces another short- and medium-term challenge: doing without Russian gas entirely by autumn 2027.
In this regard, the Cypriot Ministry of Energy emphasizes that the government intends to manage its hydrocarbon resources in accordance with its obligations as an EU member and its climate commitments, a reference to the Paris Agreement concluded at COP21 in December 2015. In practical terms, this means that natural gas is regarded as a transition fuel while renewable energy is scaled up.
Among the remaining geopolitical uncertainties, Türkiye's possible reactions will need to be watched closely. The country, which has occupied a significant part of the island of Cyprus since 1974 (around 36% of its territory), considers itself the protector of Turkish Cypriots and insists that gas resources should benefit all Cypriots, including Turkish Cypriots. In the past, Türkiye has at times sent survey vessels into the Republic of Cyprus's EEZ and, on occasion, warships to hamper the activities of foreign oil companies operating offshore Cyprus. The situation has been fairly calm in recent years, but the approaching start of gas production off Cyprus could once again heighten regional tensions. Türkiye is nonetheless isolated in the face of a Cyprus/Greece/Egypt/Israel axis. Moreover, among the three oil operators holding the key exploration licences off Cyprus, two are American giants, ExxonMobil and Chevron. It is hard to imagine Turkish authorities taking action that could threaten the interests of such companies, given that they clearly enjoy the backing of the United States. President Recep Tayyip Erdoğan is keen to maintain good relations with Donald Trump, who takes the defence of American business interests, particularly those of oil companies, very seriously. Cyprus also has strong ties with the United States, as illustrated by the 3+1 partnership bringing together Cyprus, Greece, Israel and the United States to promote cooperation in the Eastern Mediterranean in support of peace, stability and security in the region. Should pressure or threats be directed at the block 6 partners, Eni and TotalEnergies could be expected to receive support from their respective home states, Italy and France, and from the EU. These geopolitical risks have long been known and should not be underestimated, but the investment decisions taken by major oil players — or on the verge of being announced (see above) — suggest that the companies concerned regard these risks as acceptable for investment purposes, without guaranteeing that they will remain manageable.
Cyprus aims to end its electricity isolation
Cyprus is the only one of the European Union's 27 member states without an electricity interconnection to continental Europe, and its electricity prices are therefore among the highest in the region. The authorities of the Republic of Cyprus and the EU aim to change this through a future link between Cyprus and Greece. Cyprus also intends to develop electricity interconnections with the nearby Middle East. Israel and Lebanon are among the options under consideration.
In July 2026, the energy ministers of the Republic of Cyprus and Lebanon confirmed their agreement for the World Bank to conduct a pre-feasibility study to assess a possible electricity interconnection between the two countries. Cyprus and Lebanon intend to expand their cooperation to strengthen their energy ties, enhance energy security and promote sustainable development in the Eastern Mediterranean region.
The study will initially focus on an analysis of the supply–demand balance and various scenarios. In a second phase, a detailed technical and economic pre-feasibility assessment will be carried out. This phased approach will support informed decision-making.