Publications /
Opinion
Denial of the fiscal problem, or an indication of a move toward adjustment—even if a gradual one?
A week of shock for Brazilian assets. Starting Monday (Oct. 26, 2026), the real depreciated, the stock market fell, and sovereign risk premiums rose. This movement was linked to investor reactions to the election results, uncertainties regarding fiscal policy, and an international environment of high interest rates. I spent the week answering questions about whether Brazil is already in a crisis or heading toward a "hard landing."
This first week after election, the dollar climbed 8.21% on Monday, closing at R$ 5.40, and remained near that level through Friday (Oct. 30) (Figure 1). By Thursday, the Ibovespa index had fallen approximately 18.4% compared to the trading session held before the second round of the election. Sovereign risk premiums and long-term interest rates also trended upward.
Figure 1
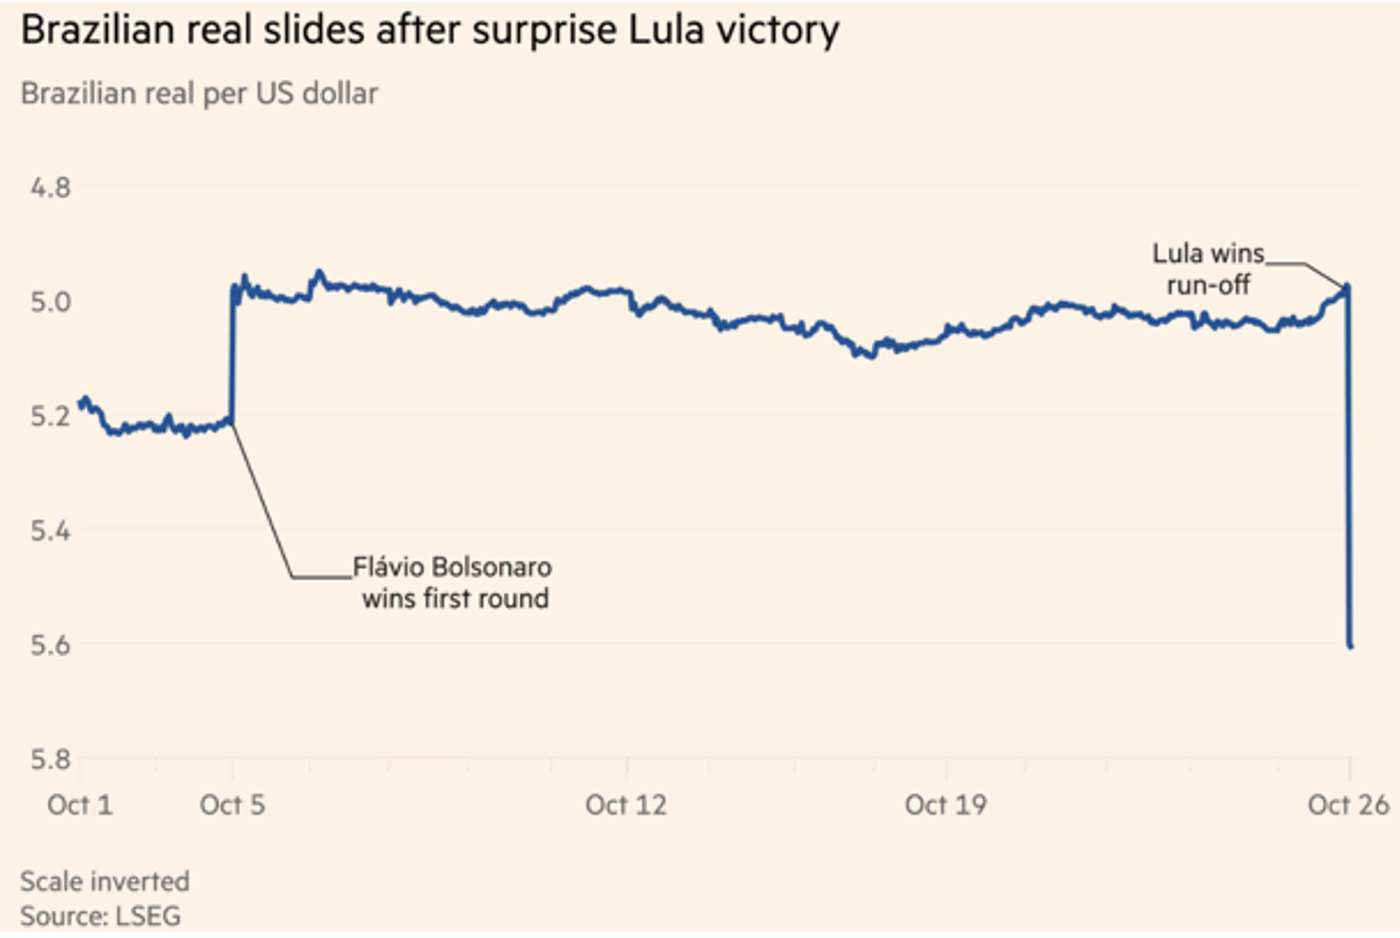
Source: Michael Pooler and Joseph Cotterill, “Lula faces a fiscal reckoning after Brazil’s market rout”, Financial Times, October 26, 2026
This is clearly one of those moments of "hyper-adjustment" in asset prices—involving "overshooting"—where the risk parameters perceived by investors shift, leading to a sudden realignment of investment portfolios. It seems evident that this stems from a prevailing perception—intensified by Lula’s unexpected victory—that the public debt-to-GDP ratio is likely to continue its upward trajectory. This, combined with high risk premiums and the interest rates demanded by bond buyers, creates a sort of "vicious cycle."
The "fiscal framework" under Lula’s third term failed to curb the deterioration of the fiscal situation. Federal primary spending rose from 17.8% of GDP in 2021–22 to 19.6% in 2023, remaining high over the following two years. With the continued growth of mandatory expenditures—a structural feature that has persisted since the early 1990s—the room for other types of spending to increase without widening public deficits has steadily shrunk.
Gross public debt is projected to rise from 72% of GDP at the end of 2022 to nearly 83% by 2026. I find the estimates by Solange Srour and the UBS Global Wealth Management team quite compelling: given Brazil’s typical GDP growth and interest rate levels, a shift in the public balance of around 4% of GDP would be required to achieve stabilization.
This figure should not necessarily be pursued to the letter—it would be unrealistic to imagine such a drastic change happening overnight—but it does illustrate just how explosive the current trajectory is if left unaddressed. This is what drives the “hyper-adjustment” in asset prices.
Marcello Estevão and Martin Castellano, from the IIF, propose that “a reasonable baseline benchmark is an improvement in the effective primary balance of at least 0.5 percentage point of GDP per year in normal conditions, subject only to an escape clause, until the surplus reaches roughly 2–2.5% of GDP” (Figure 2).”
Figure 2
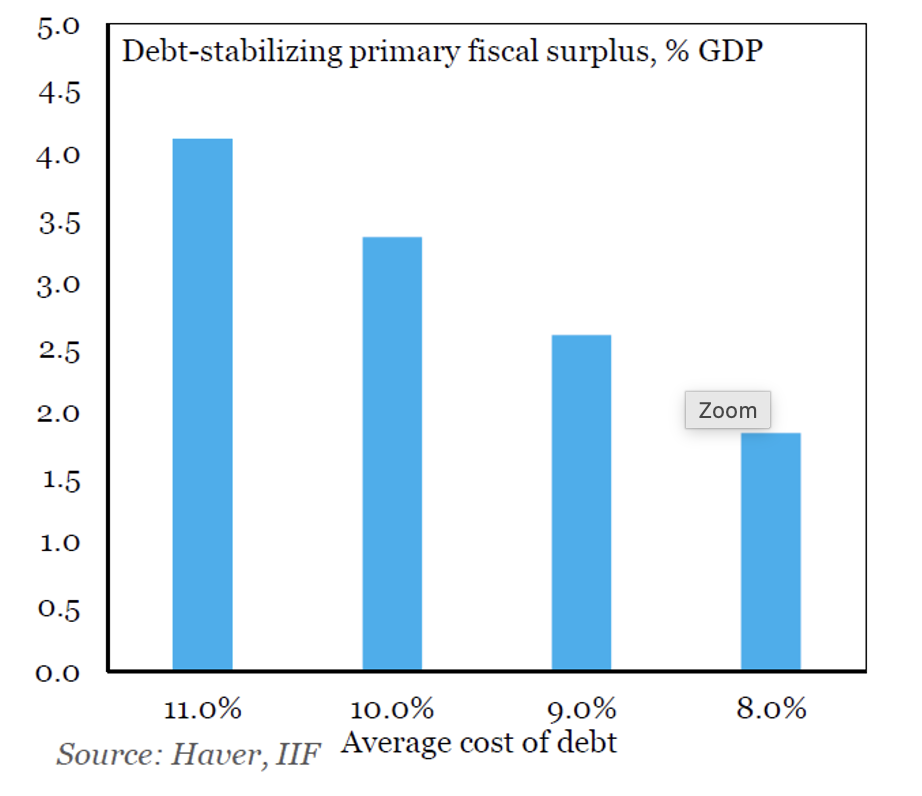
From: Marcello Estevão and Martin Castellano, “Brazil: The Fiscal Mandate After the Vote”, IIF, October 23, 2026
There are three ways to approach this issue. The first—voiced by some members of the current administration (and by Lula during his campaign)—is the notion that no fiscal adjustment is needed at all. This fantasy rests on two possible premises: 1) that public debt service can be paid in Brazilian reais without regard for the likely inflationary consequences—ignoring the fact that even domestic creditors would refuse to purchase government bonds if interest rates were artificially forced downward; or 2) the dream that investments and productivity gains could drive GDP growth to a rate higher than real interest rates. Reaffirming such a stance would only reinforce the prospect of a crisis and a “hard landing.”
A second approach would be the “Milei style”—named after the Argentine president—which entails an immediate, massive fiscal adjustment. However, a downward spiral in this direction would be self-destructive, leading to a collapse in economic growth and widespread default.
A third path would involve a gradual fiscal adjustment, encompassing all branches of government (executive, legislative, and judiciary). This would entail a phased review of expenditures based on their social efficacy and contribution to growth—reducing parliamentary earmarks, eliminating "perks" within the judiciary, and adjusting the indexation mechanisms for income-transfer programs and social security. It would not be easy, but this appears to be the only viable path.
Parallels can be drawn to the period leading up to Lula’s first term—starting in mid-2002, when markets were jittery and Lula issued his "Letter to the Brazilian People." Once in office, in addition to reaffirming his commitment to a floating exchange rate and the operational autonomy of the Central Bank, Lula raised the primary surplus target from 3.75% to 4.25% of GDP. Not only did sovereign risk premiums fall, but the country also achieved—for the first and only time to date—an "investment grade" rating from credit rating agencies (a status later lost).
Lula eased fiscal discipline midway through his second term, following the global financial crisis—a pattern repeated by the first Dilma Rousseff administration. By the time Dilma attempted a belated fiscal adjustment at the start of her second term, conditions had already turned against her (compounded by the impact of the *Lava Jato* investigation on the construction sector and the developments that paved the way for her impeachment). While Lula initially endorsed Minister Palocci’s plan during his first term, his third administration has failed to provide Finance Minister Haddad with the full conditions necessary to implement a genuine adjustment plan—with internal opposition within the government proving more effective now than it was during that first term.
Hence the critical importance of the signal regarding fiscal policy that Lula must provide at this juncture, ahead of a potential fourth term. Will he persist in denying the fiscal problem, or will he offer an indication of adjustment—even if gradual—accompanied by credible signs that the program, and those responsible for it, will not be sabotaged from within?